Tag Archives: Mean Reversion

Pairs Trading Half-Life: What 1,185 Pairs Taught Us

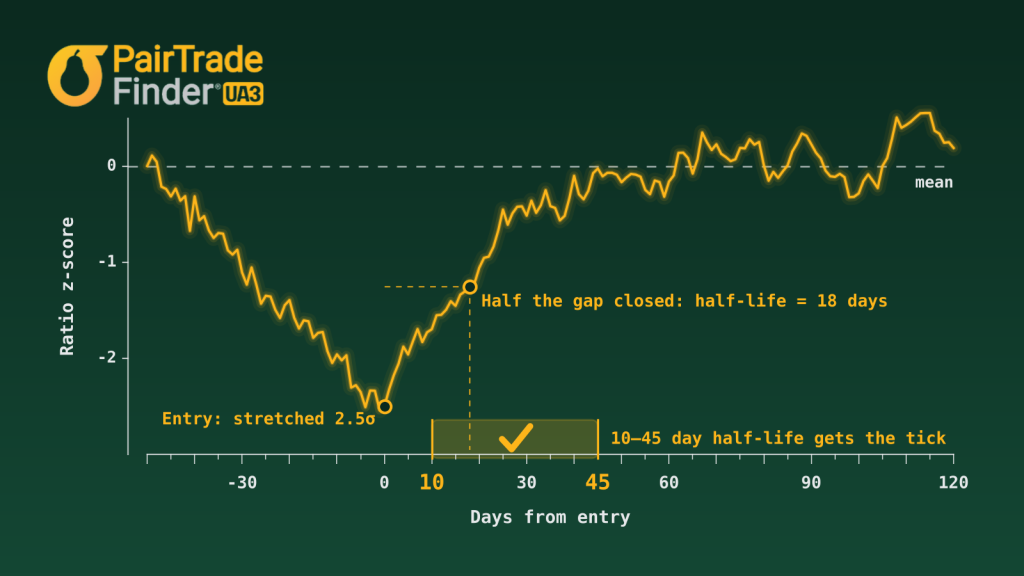
What is a pairs trading half-life?

When two related stocks drift apart, a pairs trader bets that the gap will close. The pairs trading half-life measures how long that usually takes. In other words, it is the number of days the pair needs, on average, to close half of the gap. A short half-life means the pair snaps back quickly, so your capital is tied up for days. A long one means a slow recovery and a long wait for your profit.

Our April post proposed a screen built on this measure.

… Read More →
Market-Neutral Pair Trading in Action: May 2026 Top 50 USA Stock Pair Stars

market-neutral pair trading

Most retail trading strategies depend on direction — and direction is the one thing nobody can predict consistently. By contrast, market-neutral pair trading offers an alternative: trades constructed not on whether a market rises or falls, but on the relationship between two fundamentally related assets. As a result, when that relationship temporarily diverges, mean reversion offers a measurable, repeatable edge.

Your Shortcut to Market-Neutral Pair Trading Success

This May, after another quarter of research, recalibration, and statistical validation, we are releasing the May 2026 Vintage of our Top 50 USA Stock Pair Stars.

… Read More →

Pair Trading Strategy Enhancement

Go Hybrid: Mean-Reversion Framework PLUS Technical Bias Filtering pair trading strategy enhancement

Pairs trading remains one of the most widely used market-neutral strategies, built on the principle of exploiting mean reversion in a spread constructed from two related assets. However, traditional implementations—typically based on cointegration tests and z-score entry/exit thresholds—face well-documented limitations, including instability across regimes and declining profitability in modern markets (Tenyakov & Mamon, 2017). So in this blog post we suggest our own pair trading strategy enhancement: combine cointegration and z-score based trading signals with refined technical trading indicators to create a Relative Edge indicator.

… Read More →

Kalman Filters vs. PairTrade Finder®

Why We Keep It Simple (On Purpose) Kalman filters

From time to time, experienced traders reach out and ask:

“Why doesn’t PairTrade Finder® use a Kalman filter to calculate dynamic hedge ratios?”

It’s a fair question. Kalman filters are widely used in quantitative finance and are often presented as a more advanced way to trade pairs.

So this post explains our thinking clearly.

PairTrade Finder® is designed to capture most of the statistical edge—without the complexity that often reduces real-world performance.

In practice, as a rule we seek to target a platform that delivers 80% of the benefit of institutional grade models with around 20% of the complexity.

… Read More →